Australia has one of the highest rates of share ownership in the world. According to an ASX Australian Investor Study, approximately 37 per cent of Australian adults hold shares either directly (31 per cent) or indirectly (7 per cent derivatives and 11 per cent invest in other on-exchange investments), making us a country with one of the highest rates of share ownership in the world.

Some investors find buying individual shares enjoyable and rewarding. Others may find it deadly dull, time-consuming and too risky. While there is no definitive answer as to whether you should invest in direct shares or not, your decision should be based on personal interest, financial wherewithal and your individual investment goals.

If you are thinking about taking the leap to invest in direct shares, here are some factors to consider:

Diversification is key

The ASX found that a majority of investors don’t know if their investments are diversified, or that they do not have diversified portfolios (55 per cent). This is further proven by the finding that 75 percent of shareowners only hold Australian shares.

Instead of putting all your eggs in one basket (or market) and buying shares in a single company or sector, there are a number of advantages to diversifying your investment across a variety of companies. In doing so, you can reduce your risk – when some shares struggle, others are likely to deliver stronger returns that limit your downside, giving you the confidence to remain invested even during periods of market turmoil.

But diversification involves much more than buying a collection of shares. The average Australian share portfolio is invested across five companies. If just one of those companies was consistently performing badly, that would mean that at least 20 per cent of the share portfolio is delivering negative or poor returns.

To be properly diversified, you will probably need shares that represent different company sizes, industries and locations. You will likely need to assemble shares across a group of companies that are not likely to move in the same direction at the same time. That might mean purchasing shares in dozens, or hundreds, of companies. In other words, you will not only need the resources to invest but you will also need to pay the fees on each trade.

In contrast, an exchange-traded fund (ETF) provides a low-cost diversified portfolio for as little as $500, making it a more accessible choice for many investors.

You could do a little of both, or more accurately a lot of one and a little of the other, to help with diversifying your investment portfolio. With this approach, you would invest the bulk of your funds in a managed fund or ETF to easily achieve diversification and purchase a few direct shares in small amounts on the side. This allows you to scratch that “I know this is the next big thing” itch without risking your life savings. Some financial advisers for example set up portfolios with a % allocation for the investor to use to take their direct bets.

Recognise that it’s hard to beat the market

Despite having the experience, time, and resources, the vast majority of professional investors often fail to beat market indexes. As such, a realistic perspective of your expected returns can help you manage your expectations. You should also be prepared to dedicate time to research companies so that you understand what you are investing in. Even so, history has often shown that investment success is more often delivered by time in the market, rather than by timing the market.

Understanding stock risk

You may believe you can forecast the next winning industry – technology stocks for instance. But will you be able to pick the right stock? What if, in the early 2000s, you’d bought the next WorldCom instead of buying Apple and Google? Arguably the single biggest challenge facing direct share investors selecting high-fliers before gains are built into the price.

Keep your eye on taxes

When you buy and sell shares, you may generate taxable gains. Frequent trading is likely to increase these taxes. Keep an eye on how your decisions to buy and sell may impact your tax bill.

No matter what you decide, start by identifying your goals and then create a low-cost, diversified portfolio to achieve them. (This article has focused on shares, but bonds should also play a role in most portfolios.) Then, fill that portfolio with direct shares, funds, or some combination of the two based on your interests, financial capacity and willingness to take on additional risk.


Source : Vanguard November 2019 

Written by Robin Bowerman, Head of Corporate Affairs at Vanguard.

Reproduced with permission of Vanguard Investments Australia Ltd

Vanguard Investments Australia Ltd (ABN 72 072 881 086 / AFS Licence 227263) is the product issuer. We have not taken yours and your clients’ circumstances into account when preparing this material so it may not be applicable to the particular situation you are considering. You should consider your circumstances and our Product Disclosure Statement (PDS) or Prospectus before making any investment decision. You can access our PDS or Prospectus online or by calling us. This material was prepared in good faith and we accept no liability for any errors or omissions. Past performance is not an indication of future performance.

© 2019 Vanguard Investments Australia Ltd. All rights reserved.

Important:
Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author.

Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.

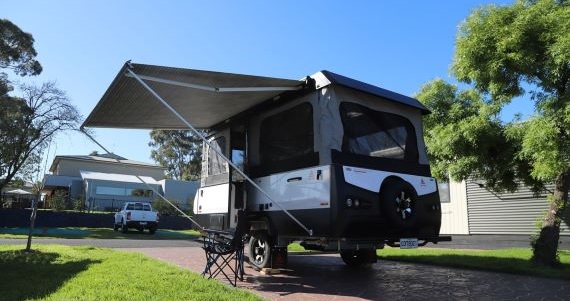
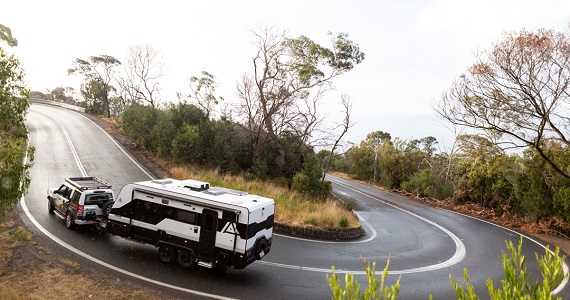
These handy hints can help you hit the road with absolute faith in your home on wheels.

Whether you’re buying a TV, a house, or a caravan, there are always questions you need to ask and answer before you purchase.

If these questions go unanswered, it can lead to problems, regrets, and inconveniences. Worse yet, it could be very costly.

To help you avoid any of this, we engaged the experts at New Age Caravans in Newcastle, who put forward a handful of key questions to consider when you’re looking to invest.

You want to be comfortable with your purchase.

1. What is your budget?

While being fixated by an exact amount can have its drawbacks, it helps to have a ballpark figure of how much you wish to spend on a van. This allows you to easily:

  • Have perspective about what you can and can’t afford.

  • Understand the difference between essentials and luxuries.

  • Narrow your search to find your preferred caravan.

We also recommend considering more than just the upfront purchase price. The resale value of the vehicle is an important consideration down the track when it comes time to sell or trade in your caravan.


It helps to quickly identify the difference between needs and wants.

2. Where are you going, and who is coming along?

Think about the intended use of your caravan and the number of people in your travelling party, as this will quickly help you find the model that’s right for you.

How many berths do you need? Does the van need bunks to accommodate all travellers? Answering these questions will help determine the size of your caravan.

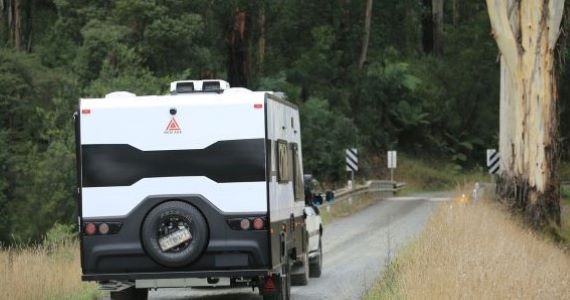
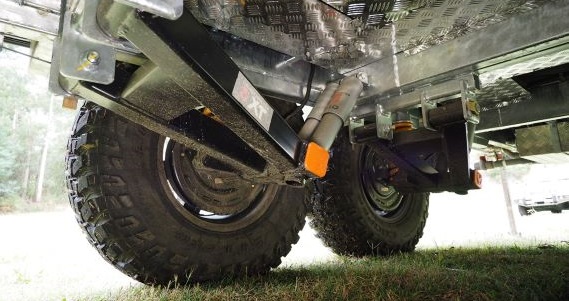
Are you sticking to the tarmac or likely hitting dirt roads? If the answer is the latter, perhaps you should consider a van with independent suspension.

Considering the size of your travelling party will go a long way to helping find the best van for you.

3. What is the quality of the caravan you are looking at?

We suggest doing research to determine how reputable your chosen manufacturer is. There is plenty of information available online, including reviews and forums.

Many promises are made at point-of-sale, but can the manufacturer deliver on them? Sometimes, it’s worth following the advice of the cliché: If it’s too good to be true, it probably is.

Quality counts for everything.

4. How long is the warranty period?

Your desired caravan might be bright and shiny now, but you will thank yourself later if take a peek at the imaginary road ahead, in case things go wrong. And one question leads to a few more!

Is the warranty offered directly from the manufacturer, or is it an insurance-type guarantee? How helpful is the manufacturer likely to be at claim time? Do they provide roadside assistance?

Dig deeper: Doing further research and/or probing the salesperson for answers often provides clarity.

If you’re second-guessing the reliability of your manufacturer, that’s never a good sign. And if the manufacturer doesn’t have complete faith in their product, then why should you?

It pays to know as much about your caravan’s warranty as possible.

5. What are the service costs?

This is a very important question, as service costs can be extreme and deter owners from regular servicing. And irregular servicing can create bigger, more costly issues. We’ve seen and heard about some terrible situations!

We advise choosing a manufacturer that offers affordable, fixed-price options so you know in advance how deep you could be digging into your pockets.

Regular servicing is essential to maximising the lifespan of your van.

6. Does the brand have a national repair network?

Whether you’re planning on doing the Big Lap or simply clocking up a few hundred kilometres in your own state, you want assurance that you can quickly and easily get help if trouble arises. And more than that, you want assistance without it costing you a fortune.

Your manufacturer should be able to easily provide you with info about its national repair network and give you peace of mind.

If trouble arises, clearly you want help as quickly and easily as possible.

7. What are the weight limits of your tow vehicle?

Caravans are just one component of a duo. And you need both parts to complement each other in order to operate properly. Gross combined mass or GCM (the combined weight of the caravan and car) and the towing capacity are important factors, yet sometimes are not understood, or ignored.

It’s vital that you comply with these weights from both a legal viewpoint as well as a safety one. Again, your manufacturer should be able to assist you with any queries about this.

The weighting game: Understanding this is vital.

Looking to buy a caravan? Check out the range at New Age now.

And when it’s time to hit the road, book your next caravanning adventure with BIG4.


Source : BIG4 Holiday Parks

Reproduced with the permission of BIG4 Holiday Parks. This article first appeared on BIG4.com.au and was republished with permission.

Important:
Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author.

Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.


Impulse purchases and buyer’s remorse often go hand in hand. But if you take a week (or a month) to reflect on your spending, you could see a noticeable boost in the funds accumulating in your savings account. Enter, the Seven-day Rule.

Don’t reply to text messages after you’ve had a glass of wine, and take a deep breath before confronting someone when you’re upset. These are both common social strategies relied upon to make you think – with reflection and clarity – before making a rash decision that could cost you something you value. Think of the ‘Seven-day Rule’ as the financial equivalent of pressing pause on your reply, or putting your phone down before hitting send.

Impulse purchases

Most of us have been in a situation where we spot something shiny and expensive that we’d really like to have: a new phone, some make-up, an expensive outfit, or maybe a new pair of skis. But in these impulse situations we often spend money based on emotions, rather than our budgeting goals. We get swept up in the excitement of having a new toy.

Many of us go ahead and make the purchase. In fact, 84 % of all shoppers have made impulse purchases, with this equating to almost 40 % of all money spent on e-commerce1. Research also shows that about half of us regret the purchase almost as soon as we’ve made it2.

Delay gratification

The goal of the ‘Seven-day Rule’ is to stop impulse purchasing, and give yourself a ‘cooling-off’ period to think about how much joy the item will bring to your life. You’re not denying yourself – you’re just delaying the potential gratification.

The idea is surprisingly simple: If you see something you want to buy, but haven’t budgeted for it, walk away for a week.

Over this time, ask yourself if you really need the item. If, after seven days, the answer is yes, you can go back and buy it. If you’ve forgotten about it, then your time away from the stores has saved you from facing buyer’s remorse.

Cooling-off period

When you’ve put the item back on the shelf (or closed that online shopping browser), do a few things:

  • Write what you want to buy on a piece of paper, along with the price, date and store name.

  • Stick the note on your fridge, so you can re-address it in a week.

  • Do some further research online – chances are you can find significant discounts or better models elsewhere.

  • You could then consider transferring the cost of the item from your everyday bank account to your savings account.

  • Do you really want to buy that jacket in a week and spend money that is now going toward a larger savings goal, like purchasing a new car?

The ‘30-day rule’

The Seven-day Rule concept won’t work for every purchase you make, so set yourself a financial hurdle – say, walk away if the item in question costs more than $100. Then make this hurdle scalable: if your potential purchase is $300 or more, elevate the cooling-off period to 30 days.

Giving yourself a month to evaluate your spend also means you have the time to set yourself a financial challenge. Say you have your heart set on a pair of shoes that costs $350. Rather than taking the money from your savings account, why not see if you can save that amount from scratch?

For example, you’d need to set aside around $12 a day for 30 days to save $350. Check out the articles below for tips on how to save money on everyday items.

Please contact us on Phone: 07 5641 4134 if you seek further discussion on this topic.


1-2 https://www.invespcro.com/blog/impulse-buying/

Source : AMP January 2020

Important:
This information is provided by AMP Life Limited. It is general information only and hasn’t taken your circumstances into account. It’s important to consider your particular circumstances and the relevant Product Disclosure Statement or Terms and Conditions, available by calling Phone: 07 5641 4134, before deciding what’s right for you.

All information in this article is subject to change without notice. Although the information is from sources considered reliable, AMP and our company do not guarantee that it is accurate or complete. You should not rely upon it and should seek professional advice before making any financial decision. Except where liability under any statute cannot be excluded, AMP and our company do not accept any liability for any resulting loss or damage of the reader or any other person. 

What types of life insurance are offered by super funds?

Super funds typically have three types of insurance for members:

  • Death cover (also known as life insurance) – is part of the benefit your beneficiaries receive when you die, either as a lump sum or as an income stream.

  • Total and permanent disability (TPD) cover – pays you a benefit if you become seriously disabled and are unlikely to ever work again.

  • Income protection (IP) cover – pays you an income stream for a specified period if you can’t work due to temporary disability or illness.

Your employer’s default super fund will generally provide you with death and TPD cover. This basic cover may be available without health checks. You can usually increase, decrease, or cancel your default insurance cover.

Your super fund’s website will have a product disclosure statement (PDS) which explains the insurer they use and details of the cover available.

Like other insurance policies, you will pay insurance premiums. If your insurance is through your super fund, the premiums are deducted from your super account balance.

Cancellation of insurance on inactive and low balance accounts

Super funds will cancel insurance on:

  • inactive accounts that haven’t received contributions for at least 16 months

  • accounts with balances less than $6,000 from 1 April 2020.

Your fund will contact you if your insurance is about to end.

If you want to keep the insurance, you must tell your super fund or make a contribution to that account. You may want to keep your insurance if you don’t have any through another fund or insurer and you have a particular need for it (e.g. you have children or other dependents or work in a dangerous job).


Insurance for people under 25

From 1 April 2020, insurance will not be provided if you’re a new super fund member aged under 25 unless you:

  • write to your fund to request insurance through your super

  • work in a dangerous job – your super fund will give you the option to cancel this cover if you don’t want it.

Why get life insurance through your super?

There are benefits in getting your life insurance through super:

  • It’s often cheaper because super funds purchase insurance policies in bulk

  • You can get the cover you need for you and your family, even if money is tight

  • It’s easy to manage because premiums are automatically deducted

  • Some funds automatically accept you for cover without requiring a health check

  • You can usually choose the amount you want to be covered for

However, you also need to be aware that:

  • Limited cover – The types of insurance, and level of cover, may be limited. Cover is not tailored to your circumstances and exclusions may apply. If you want more insurance, you can apply to increase your cover and a medical may be required. If you want a different type of cover, you may need to get this outside super. Check the PDS carefully.

  • Not portable – If you change super funds; have an extended absence from your employer; your employer’s super contributions stop or your account balance drops below a certain amount, your cover may cease and you could end up with no insurance. Always read the information sent to you by your super fund as they may be alerting you to changes to your cover.

  • Slower to pay – There can be delays in receiving benefits as the insurer pays the benefit to the fund first, who then distributes it to you or your beneficiaries.

  • Who gets paid – If you do not make a binding beneficiary nomination, or your fund does not offer binding nominations, the super trustee will decide who gets your benefits when you die, although your nomination will be taken into consideration.

  • Ends at around age 65 – Life insurance coverage through super ends when you reach a certain age (usually 65 or 70). Policies outside of super may cover you for longer.

  • Reduces super balance – The cost of insurance premiums are deducted from your super balance, reducing the money available for your retirement.

  • Multiple super accounts – If you have more than one super account, you may be paying premiums on multiple insurance policies. This could reduce your retirement money, especially where you can only claim on one policy. Find out if you are able to claim on more than one policy, and consider which policy you might cancel. Even if you can claim on more than one policy, consider whether you need more than one policy or whether you can get enough insurance through one fund.

  • Premiums may increase when you change jobs – Even if you stay with the same super fund when you leave your employer, you may be moved to the personal division of that fund which could increase your premiums for the same cover. Some funds default members as smokers or blue-collar workers when they move between divisions of funds, which could significantly increase premiums, and further reduce your retirement money. Check your annual statement to see how you have been classified, and contact your fund if you think the incorrect classification has been given to you.

You may opt for some cover through your super fund, and some cover directly from a life insurer, depending on the cost and the type of cover you need.

Check your life insurance cover before changing super funds

Before switching or consolidating super funds, make sure you can get the death, TPD or income protection cover you want, in your chosen fund. Be particularly careful if you have a pre-existing medical condition or are aged 60 or over, as you may not be able to get insurance again without health checks. Seek financial advice if you are unsure.

How to check the insurance you have through super

To find out what life insurance you have with your super, either call your super fund, check your annual super statement or access your super account online to check:

  • what type of insurance cover you have

  • how much cover you have, and

  • how much you are paying for the cover. 

You should also find out how your super fund is calculating your insurance premiums. For example, if your super fund has classified you as a smoker or blue collar worker, and these risk characteristics aren’t relevant to you, you could be paying more for your insurance than you need to.

You may need to call your super fund to check how you’ve been classified as your annual statement may not provide this detail.

What if you have no insurance through super?

If you discover that you have no insurance through your super fund, and you think you should have cover, call your super fund to find out why and discuss your options.

Claiming on insurance through super

There are some important things you need to know if you’re making an insurance claim through super.

Making a claim

To make a claim for insurance through your super fund you will typically need to submit a claim form. If you die, your estate or dependants should contact the super fund to find out how to claim death benefits.

Most super funds provide claim forms on their websites or you can call them and ask them to send you one.

When you make your claim, you may be asked to provide documentation that proves your condition, including medical reports. There may be waiting periods in some cases.

Some funds will allocate you a claims officer to be your point of contact if you have any questions during the claims process.

Unhappy with your super fund’s claims process?

If you’re unhappy with the claims process or unhappy because your claim is not accepted, complain to the super fund using its formal complaints process. Your super fund’s website should have details about how to complain. If not call and ask about the process, or look in the product disclosure statement.

If you’re not satisfied with the outcome, take your complaint to the Australian Financial Complaints Authority (AFCA). AFCA will generally not consider the matter unless you have used the superannuation fund’s internal complaint process first.

AFCA replaced the Superannuation Complaints Tribunal (SCT) on 1 November 2018. Complaints lodged with the SCT before this date will still be dealt with by the SCT.

You do not need a lawyer to complain to your fund or to AFCA. Of course, you may find it helpful to use a lawyer or other professional adviser if you think the benefits outweigh the fees.

Industry Code of Practice

An Insurance in Superannuation Voluntary Code of Practice started on 1 July 2018 to improve the consumer experience of insurance in superannuation. If your fund’s trustee agrees to comply with the Code, you should get better disclosure and claim and complaints handling. Your fund trustee should notify you if it is complying with the Code. You can check this on your fund’s website.

To decide if insurance through super is right for you, work out how much cover you need, whether your super fund will offer you this cover, and compare the costs and conditions with other insurance providers.

Please contact us on Phone: 07 5641 4134 if you seek further discussion on this topic .

Source : ASIC’s MoneySmart 

Reproduced with the permission of ASIC’s MoneySmart Team. This article was originally published at www.moneysmart.gov.au/superannuation-and-retirement/how-super-works/insurance-through-super#PMIF
Important note: This provides general information and hasn’t taken your circumstances into account.  It’s important to consider your particular circumstances before deciding what’s right for you. Although the information is from sources considered reliable, we do not guarantee that it is accurate or complete. You should not rely upon it and should seek qualified advice before making any investment decision. Except where liability under any statute cannot be excluded, we do not accept any liability (whether under contract, tort or otherwise) for any resulting loss or damage of the reader or any other person.  Past performance is not a reliable guide to future returns.

Important
Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author.

Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.


There are plenty of good reasons why Australian investors feel more comfortable investing at home. Investing overseas is unfamiliar. Foreign exchange movements often feel like too much of a risk. Overseas companies can be difficult to get information on. Sometimes they operate in different languages.

It’s understandable that we prefer investing at home but this preference often comes at the cost of returns.

Home bias – as it’s called – affects many local investors. In fact, three in four Australian share investors hold only Australian shares.

It’s a problem not just because of the small size of the Australian market, which is less than 2 per cent of global market capitalisation, but also because it creates a natural bias in portfolios against certain industries and in favour of others.

The local securities market is heavily weighted towards banks and resource companies, so they will naturally make up a large portion of many investors’ portfolios unless they have taken active steps to avoid it. Compared to the world’s largest market, the United States, Australia is low on big tech, communications and healthcare, leaving many investors underexposed to those important industries.

It matters because it can impact performance.

Whilst Australian shares have provided investors with significant aggregate returns over the last thirty years, when compared to other major asset classes on a year by year basis, they have actually been the top performer in only three of those years, and were the lowest performing asset class twice during this same period.

So what’s the alternative?

One option is investing directly overseas by buying shares on a foreign securities exchange. It gives an investor direct exposure to foreign shares and these days is cheaper and easier than ever. But it remains more costly than investing at home and normally comes with tax implications that can be complicated and could necessitate paying for expert advice.

The big Australian companies that operate globally are also sometimes seen as way to effectively reduce exposure to Australia. Miner, BHP, earns around half of its revenue from China, so buying BHP shares exposes an investor to the fast-growing Chinese economy.

But they are a small group of companies, mostly in the mining, oil and gas and health sectors, and investors still end up with an overly concentrated portfolio. Australian companies also have a patchy record overseas – although some of the current crop are indeed superstars.

A better alternative is a managed investment, which can offer access to a basket of international companies in one purchase. A range of exchange traded funds track international share indexes – and some are actively managed.

Listed investment companies and the newly emerging listed investment trusts offer similar options while a vast range of unlisted managed funds are also available.

The key to success is diversification – buying a portfolio of hundreds or thousands of companies around the world eliminates home bias and reduces the resulting risk by reducing your exposure to a single event, company, industry or country.

Unfortunately, as a nation we’re still not listening to that message.

The ASX conducts a biennial study into investor behaviour. The last study, in 2017, surveyed 4000 people. One of the headline findings was we are still not very well diversified. The study also found many of us don’t really even understand what diversification means.

Three-quarters of us hold only Australian shares, but almost half (46 per cent) claimed to be diversified even though they held less than three investment products.

Source : Vanguard November 2019 

Written by Robin Bowerman, Head of Corporate Affairs at Vanguard.

Reproduced with permission of Vanguard Investments Australia Ltd

Vanguard Investments Australia Ltd (ABN 72 072 881 086 / AFS Licence 227263) is the product issuer. We have not taken yours and your clients’ circumstances into account when preparing this material so it may not be applicable to the particular situation you are considering. You should consider your circumstances and our Product Disclosure Statement (PDS) or Prospectus before making any investment decision. You can access our PDS or Prospectus online or by calling us. This material was prepared in good faith and we accept no liability for any errors or omissions. Past performance is not an indication of future performance.

© 2019 Vanguard Investments Australia Ltd. All rights reserved.

Important:
Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author.

Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.

Looking to reduce your impact on the environment and save money? Making your kitchen more eco-friendly helps both the planet and your bank account! Use the tips below to save money in the kitchen and help save the planet. 


1. Plan Meals in Advance

A little planning goes a long way! Set aside time each week to plan your meals. List exactly what ingredients you’ll need for each meal and add them to your grocery list. This step alone will help you avoid unnecessary purchases at the store. Having a weekly menu also reduces the temptation to order take out or go out to eat.

2. Eat Leftovers

A little planning goes a long way! Set aside time each week to plan your meals. List exactly what ingredients you’ll need for each meal and add them to your grocery list. This step alone will help you avoid unnecessary purchases at the store. Having a weekly menu also reduces the temptation to order take out or go out to eat.

3. Reuse Kitchen Scraps

Many kitchen scraps can be reused and repurposed for different recipes. For instance, you can use leftover vegetables or chicken bones to make homemade broth and stock. 

Some other ways I repurpose old food is turning stale bread into croutons for salad and using overripe bananas to make banana bread. Look for ways you can use foods that you would otherwise throw out for different dishes. Check out the Zero Waste Chef for more ideas on how to reduce food waste.

4. Make Homemade Sauces and Condiments

Buying common sauces, and condiments like mustard and salad dressing can add up. Plus, most of these items come in single-use plastic containers which are awful for the environment. 

Instead of buying condiments at the store, try making them from scratch. There are a ton of homemade recipes online that are fun and taste better than the bland sauces you’d normally buy!

5. Skip the Dry Cycle on your Dishwasher

Kitchen appliances are no doubt convenient, but the energy they use has a negative impact on the environment… not to mention makes your electric bill shoot up! Thankfully, there are ways to enjoy these items while minimizing their negative side effects. 

One way to do this is to skip the “dry cycle” on your dishwasher. When it’s time for your dishes to dry, simply open your dishwasher door or grab yourself a drying rank and let the dishes dry off naturally.

6. Don’t Store Hot Items in your Refrigerator

Like your dishwasher, your refrigerator zaps up a lot of energy in the kitchen. There are a number of ways to reduce the amount of power your fridge uses. For a quick win, a great tip is to ensure your fridge or freezer temperature isn’t set too high. The most efficient temperature setting for your freezer is -18°C and your fridge between 2°C and 5°C. It’s also important to leave some space around the back of your fridge or freezer for air to circulate.

Another quick win is to stop putting hot food in the fridge. Warm items increase the temperature in your refrigerator. This causes your fridge to use more power to bring the temperature down to normal. Next time you want to store hot leftovers, let them cool down first before putting them in your fridge.

7. Unplug Kitchen Appliances that aren’t in use

Keeping items plugged into an outlet uses energy; even if they’re not turned on. How many kitchen appliances do you keep plugged in when they’re not in use? While you may not be able to power off your refrigerator, there are many smaller appliances that you can unplug. 

Look around your kitchen and see what appliances you leave plugged in. You’ll be surprised at how many you find. Some common ones I’ve noticed are microwaves, coffee makers, and toasters. This may sound trivial, but little steps like this can add up to significant savings.

8. Stop Using Paper Towels

How often do you buy paper towels? When I crunched the numbers, I was shocked to learn how much I spent. Removing paper towels from your kitchen saves you a ton of money. Plus paper towels are one of the most wasteful single-use products you can buy!

Instead of cleaning your kitchen with paper towels, invest in a set of kitchen towels. If you’re really looking to go green you can also cut up old clothes or bed sheets and use them as DIY kitchen towels. Leave a basket of rags on your counter and reuse them over and over.

9. Bulk Bin Shopping

Shopping at the bulk bin section of your grocery store is a great way to save money. You can get discounted prices on items like rice, spices, and dried fruit when you buy in bulk. Bulk bin shopping also helps you avoid the plastic packaging that many of these items come wrapped in. Most stores offer plastic produce bags to use for the bulk bin section, so by grabbing some reusable bags you can avoid contributing to the plastic bag problem.

10. Start a Garden

Gardening is a cheap alternative to buying produce at the store. It also limits the negative impact shipping produce has on the environment. Not only that, it feels great knowing you are cooking with fresh, organic ingredients.

If you don’t have space for a garden in your home, try looking for community gardens in your area. I can’t recommend community gardening enough! It’s a sustainable way to grow food and helps you connect with the people in your neighborhood.

Saving money and saving the planet go hand in hand. Use one of the suggestions above to help the environment while cutting down costs in your kitchen!


Source : FOODMATTERS

Reproduced with the permission of the Food Matters team. This article by Megan Kioulafofski  was originally published at https://www.foodmatters.com/article/10-ways-save-money-kitchen-and-save-planet

Important:
This provides general information and hasn’t taken your circumstances into account.  It’s important to consider your particular circumstances before deciding what’s right for you. Although the information is from sources considered reliable, we do not guarantee that it is accurate or complete. You should not rely upon it and should seek qualified advice before making any investment decision. Except where liability under any statute cannot be excluded, we do not accept any liability (whether under contract, tort or otherwise) for any resulting loss or damage of the reader or any other person. 

Any information provided by the author detailed above is separate and external to our business and our Licensee. Neither our business nor our Licensee takes any responsibility for any action or any service provided by the author.

Any links have been provided with permission for information purposes only and will take you to external websites, which are not connected to our company in any way. Note: Our company does not endorse and is not responsible for the accuracy of the contents/information contained within the linked site(s) accessible from this page.

Movements on the global and domestic stage in 2019 have driven home some tried-and-tested lessons in investing, markets, and keeping your cool.
Each year, we see new leaders, new policies, and new conflicts which impact markets. At the ground level, it can be tempting to get caught up – or overwhelmed – by the micro.

However, if we take a look at some key themes and events from the year that was, we see that some evergreen investment principles have yet again applied to 2019, and likely will for 2020.

2019 in hindsight

1. Highs and lows

Seasoned investors will be familiar with Warren Buffett’s much-used quote: “Be fearful when others are greedy, and greedy when others are fearful.” A retro look at the last 12 months tells us, yet again, that expression rings true.

This time a year ago, there was a lot of negative sentiment about share markets. At home and overseas, shares fell sharply until about Christmas last year. By Christmas eve, the US share market had fallen 20 per cent from its high in September.

By the start of this year, markets had promptly turned around, and this year turned out to be a reasonably good year for share markets. It was a classic case of the market bottoming out when negative sentiment had reached fever pitch.

2. Negative noise

Throughout 2019, there have been several significant negatives that we could point to. Global debt is high and unemployment is rising. Those factors are contributing to heightened social tensions, which are seeing a rise in populist leaders, and a backlash against what many would consider ‘sensible’ economic policies.

Without doubt, as a result, there are events happening globally that are rattling markets. The trade war with the US and China is a fitting example of that – two global superpowers swinging between stalemate and vitriol has directly impacted markets and confidence.

Despite the backdrop of major events like the trade war, there are several other factors which counter the negative. For example, inflation is still low, and interest rates the world over are still low. We know that these conditions make for good investment returns. We are also seeing an unprecedent spike in technological innovation globally. Also, there is rapid growth in middle class populations throughout Asia. All of these things contribute to market opportunities, and should be considered just as much as the black spots.

3. Begin with the end in mind

The hunt for yield this year has been a hunt indeed. There is a lot of anxiety about the implications of the lower-for-longer environment on retirees.

The key question here is: what is most important to you? Is it the absolute security of your investment? In that case, you have to wear the low yields for now, and get the guarantee of a cash holding.

Many investors have realised though that they’re not getting much out of their bank deposits, and shifted their money to shares or real and unlisted assets. I sense a preparedness on the part of these investors to recognise that while share values can move around, and there are risks in markets like commercial property and infrastructure, the income flow is relatively stable.

In short, to me, the most important thing for self-funded retirees to consider in this environment is whether their priority is absolute security or steady income, and then to work backwards from that.

4. Housing hype

If 2019 taught us anything about residential property in Australia, it’s that just because housing is expensive and household debt levels are high, doesn’t mean house prices are going to crash.

The market turnaround, which kicked off around the middle of the year, also reminds us that there is strong underlying demand in our housing system. It took a few tweaks – like the election outcome and resultant confirmation that the tax system will remain unchanged for property investors and rate cuts – to spark confidence.

We continue to see an unmet underlying demand for housing in Australia. There is often talk of huge supply coming onto the market, and a jump in vacancy rates. This may be the case in some instances, but the key considerations include whether that supply is meeting demand in areas people want to live in, and if the supply is intended for everyday life (for example, it’s not a holiday home.) And most importantly, whether the supply is enough to match strong population growth.

5. Don’t discount the US

At this point in history, despite the growing global force of China, the US continues to dominate in terms of influence on global markets.

We could point to some hard examples of this, such as during the tech wreck in the early 2000s. The US went into recession at that time, and although Australia did not experience recession, our share market still got hit.

A perhaps more relatable example is in day-to-day life. I would venture a guess that even the most seasoned investors would be more in tune with the movements of the US share market on a daily basis than the Chinese share market. If the US share market has a bad day, we brace for it in Australia – it’s in the news, futures will have come down, and awareness is raised. If Chinese shares have a bad day, it might get a mention, but it’s nowhere near as big of an issue.

So, even though in relative terms the US economy has declined, this year has again proven it continues to punch above its weight.

2020 vision

For the year ahead, there’s a few themes market watchers should keep an eye on. Here’s a few for you to consider.

1. The global economic cycle

For me, the key issue next year will be the global economic cycle. As it stands, we expect that global economic growth will pick up again, in response to monetary easing that we’ve seen this year, therefore avoiding a recession at home and abroad. Should that materialise, it will likely result in decent market gains.

2. Pressure at home

In Australia, growth is sluggish, and the economy is running below its potential. This creates an argument for further policy stimulus. We have already seen the government introduce staged tax cuts from early next decade – it’s likely that these could be brought forward.

But assuming this does not occur quickly enough, we also expect to see two more cash rate cuts between now and February, bringing the official cash rate down to 0.25 per cent, which we believe will be its bottom. Any further cuts would unlikely have the desired impact, as banks have already not been passing on the recent drops in full.

The scope for extra stimulus is one of a mix of reasons we don’t foresee a recession next year. There are still measures up the government and Reserve Bank’s sleeve to prevent it.

3. The US and China trade war

The race for the US presidency next year could prompt a short-term turnaround from Trump in this long and drawn-out trade war with China.

History tells us that presidents aren’t re-elected if they let the economy slide into recession, or if unemployment spikes in the run up to the election. Trump wants to get re-elected, and he will be under pressure to put the trade war on hold for a year at least, which he could claim as a win for his leadership and hopefully, the US economy. Further, any good news Trump can announce during the presidential race represents a win for his campaign.

In addition, there is reason for China to want the trade war to settle. The Chinese economy has slowed down, and trade battles don’t help in that context. Also, there’s a risk for the Chinese government that they will be negotiating with a tougher Trump if he is re-elected, into what would be his second and final term.

In the long-term, the ongoing battle between these superpowers is unlikely to dissipate. In short, it has tell-tale signs of the so-called Thucydides Trap, in which a rising power and an incumbent power go to war (of sorts) where there is threat of displacement. This has its origins in the fear felt and acted on by Sparta during the rise of Athens. Fortunately, given both China and the US are nuclear powers a hot war is thankfully unlikely, but some sort of cold war is a high risk.

4. Local politics in the US

The US election is next year, marking the end of Donald Trump’s first term in office. He is now fighting for a second and final term, and has history on his side along with current betting market odds. Often with share markets, it’s a case of better the devil you know. A Trump re-election shouldn’t rattle share markets too much, nor should a victory from a more centrist candidate, like Joe Biden. However, if victory goes to the left, the share market would get nervous.

At the same time, there are impeachment proceedings against Trump. In public, this is amplifying significantly against Trump. Recently US speaker of the house, Nancy Pelosi, has implied Trump’s actions were worse than those of Richard Nixon, who resigned amidst the scandal of Watergate. Still, at this stage it appears unlikely that the upper house would vote to remove Trump from office (as 20 Republican senators would need to desert him), but the whole saga has the potential to rattle markets.

5. Brexit and Boris Johnson

October 31 this year was supposed to be the UK’s “do or die” Brexit Day. Instead, the UK’s Prime Minister Boris Johnson has successfully called a general election in an attempt to break the Brexit stalemate.

All major parties look to be entering the election supporting a soft Brexit or none at all, meaning the risks of a hard Brexit are diminished. Nonetheless, markets will be watching this closely in the months to come. And even if a short-term soft Brexit is agreed to, it could still return as an issue if the UK and EU fail to negotiate a long-term free trade deal by the end of a transition period

The biggest risk for the UK is if the UK leaves with no agreement in place. If this occurs, the UK will break all trade ties overnight and likely revert to World Trade Organisation rules while independent trade agreements are negotiated. This could be disastrous for the US in the short term as 46% of UK exports go to the EU (against 6% of EU exports which go to the UK).

Keep calm and carry on

I have been working in and around investment markets for 35 years now. A lot has happened over that time in Australia and overseas. A few things that come to mind include the 1987 crash, the recession Australia had to have, the Asian crisis, the tech boom/tech wreck, the mining boom, the Global Financial Crisis and the Eurozone crisis. There was also the end of the cold war, a long period of US domination and now the rise of Asia and China.

As the saying goes, the more things change, the more they stay the same. This will remain true of investment markets going into 2020. It’s important to see through the noise, hold a steady hand, and remember that the crowd can panic and get things horribly wrong.

I recently wrote about the nine most important things I’ve learned in my career, which you can read more about it here. I expect these golden rules to apply for the years to come.


Author: Dr Shane Oliver, Head of Investment Strategy and Economics and Chief Economist, AMP Capital Sydney, Australia

Source: AMP Capital 20 Jan 2020 

Important notes: While every care has been taken in the preparation of this article, AMP Capital Investors Limited (ABN 59 001 777 591, AFSL 232497) and AMP Capital Funds Management Limited (ABN 15 159 557 721, AFSL 426455) (AMP Capital) makes no representations or warranties as to the accuracy or completeness of any statement in it including, without limitation, any forecasts. Past performance is not a reliable indicator of future performance. This article has been prepared for the purpose of providing general information, without taking account of any particular investor’s objectives, financial situation or needs. An investor should, before making any investment decisions, consider the appropriateness of the information in this article, and seek professional advice, having regard to the investor’s objectives, financial situation and needs. This article is solely for the use of the party to whom it is provided and must not be provided to any other person or entity without the express written consent of AMP Capital.

 

In this paper, we explore the material ESG issues we are facing globally, the key drivers for action, and the important role that the real estate industry, asset owners, customers, partners and the community have to play in driving change that delivers positive outcomes, while ensuring the assets we manage at AMP Capital continue to perform a long way into the future.

Read the White Paper

DOWNLOAD NOW


Author:  Chris Nunn, BA, LLB, MSc Head of Sustainability – Real Estate Sydney, Australia

Source: AMP Capital 16 Jan 2020

Important notes: While every care has been taken in the preparation of this article, AMP Capital Investors Limited (ABN 59 001 777 591, AFSL 232497) makes no representation or warranty as to the accuracy or completeness of any statement in it including, without limitation, any forecasts. Past performance is not a reliable indicator of future performance. The information in this document contains statements that are the author’s beliefs and/or opinions. Any beliefs and/or opinions shared are as at the date shown and are subject to change without notice. This article has been prepared for the purpose of providing general information, without taking account of any particular investor’s objectives, financial situation or needs. It should not be construed as investment advice or investment recommendations. An investor should, before making any investment decisions, consider the appropriateness of the information in this article, and seek professional advice, having regard to the investor’s objectives, financial situation and needs.This article is solely for the use of the party to whom it is provided and must not be provided to any other person or entity without the express written consent of AMP Capital.
https://vimeo.com/371515683

The market backdrop

Investors are resetting expectations for returns amidst continuing pressures in the economic environment as the world continues to experience global political uncertainty, sluggish economic growth and trade tensions between economic powerhouses. Interest rates are now expected to remain lower for longer than first anticipated.

In this context, investors are turning to asset classes better able to deliver attractive returns. In particular, they’re seeking out investments that exhibit defensive characteristics. There has also been significant growth in global assets under management, underpinned by the growth in the middle class of developing nations.

Market reactions and considerations

As a result, investors are continuing to direct cash flows to non-residential real estate.

There is some difficulty in this approach. Globally, investors are under-allocated – unable to place all targeted allocations to real estate – and seeking to increase these targeted allocations. However, the scarcity of this asset class means the investable universe is somewhat fixed and, unlike other asset classes such as bonds, there is no unlimited supply to meet investor demand.

For example, there are only 18 premium office buildings in Sydney, Australia and six in Melbourne, Australia. A global investor interested in the best assets in the largest markets of the Australian office sector will find the potential of that market restricted.

Patterns worldwide

This imbalance in supply and demand is driving commercial real estate asset values across the globe. While record high pricing has tempted us to call the peak of the market over the last three years, the attractiveness of the sector amidst such uncertainty and volatility means we expect the cycle to continue to extend.

Historically, real estate investment has been dominated by investment in the office and retail sectors, however as part of this search for supply we are witnessing a shift towards logistics as well as growth in demand for non-traditional sectors.

The logistics sector has benefited from a number of factors, including the growth in e-commerce, improvements to the supply chain, the increased use of robotics, and savings in transportation costs by being located close to the customer. Property is typically a smaller part of the cost structure of an online retailer, and the benefits of proximity allow substantial capacity for these businesses to pay more for well-located accommodation.

Whilst the outperformance of logistics is attractive, it is a sector that is difficult to scale up – there is only a certain amount of suitable property located in close proximity to large residential centres. Given these constraints, the next port of call for investors are non-traditional sectors that look set to be beneficiaries of global mega-trends.

Examples of this abound. The exponentially increasing global demand for data will require a vast expansion of capacity and in many cases different model of communications infrastructure, such as the proliferation of edge data centres that looks set to accompany the move to autonomous mobility. An increasingly urbanised population and declining levels of housing affordability is fuelling demand for alternatives, such as high-quality manufactured housing. A rapidly ageing population and a shrinking taxpayer base is shifting the onus for aged care provision onto the private sector.

This diversification of cash flows into real estate has led to the compression of yield spread between the more traditional sectors and these newer investable sectors.

Further investment in these sectors will broaden this diversification and more effectively disperse risk across real estate, with different factors driving performance in each sector. Under this new model of real estate investment, management expertise becomes increasingly important as opportunities open up that are outside of the traditional sectors and, in many cases, further up the risk curve.

With capitalisation rates at record lows, driving income and managing risk have become key to growth. Performance is increasingly specific to the asset concerned, opportunities are more difficult to identify to the casual investor, and the management of environmental, social and governance (ESG) considerations are paramount to achieving sustainable value.

Real estate is a sector exposed to considerable regulatory influence, entailing both upside and downside risk. The consideration of ESG factors, especially in the current political climate, is unavoidable, and should be ingrained in the active management of the asset, at every point of the buy-hold-develop-sell cycle.

As the world grapples with uncertain prospects across a number of other asset classes, the outlook for non-residential real estate remains distinctly positive, with sound property market fundamentals still at play, and investors continuing to be attracted to the defensive characteristics of this asset class.


Author: Claire Talbot, Fund Manager – Real Estate Sydney, Australia

Source: AMP Capital 20 Jan 2020

Important notes: While every care has been taken in the preparation of this article, AMP Capital Investors Limited (ABN 59 001 777 591, AFSL 232497) and AMP Capital Funds Management Limited (ABN 15 159 557 721, AFSL 426455) (AMP Capital) makes no representations or warranties as to the accuracy or completeness of any statement in it including, without limitation, any forecasts. Past performance is not a reliable indicator of future performance. This article has been prepared for the purpose of providing general information, without taking account of any particular investor’s objectives, financial situation or needs. An investor should, before making any investment decisions, consider the appropriateness of the information in this article, and seek professional advice, having regard to the investor’s objectives, financial situation and needs. This article is solely for the use of the party to whom it is provided and must not be provided to any other person or entity without the express written consent of AMP Capital.
 

https://vimeo.com/377459230

To the relief of homeowners, the Australian market has performed exceptionally in the second half of 2019. This much-anticipated change in direction for the housing industry has set the tone for the year ahead.

The road so far

In May the Coalition government unexpectedly won the federal election, which removed some of the risks around potential changes to property taxation; then the RBA resumed a program of monetary easing; and finally, the Australian Prudential Regulation Authority (APRA) announced it had reduced the interest rate used for bank serviceability when assessing household mortgages.

In combination, these occurrences triggered a recovery in Australian house prices from the middle of the year, and they’ve strengthened further over the past couple of months. The increase was a welcome change after consecutive month-on-month declines for nearly two years.

In looking at recent trends in the housing market, it does appear as if Sydney and Melbourne property prices will likely rise by about 10-15% over the next six to twelve months (which is heavily predicated on the likelihood that RBA will continue to cut interest rates).

Therefore, there are three key concepts that should guide our thinking around the housing market in the near-term.

What could be on the cards?

First, we anticipate the RBA will announce in early 2020 another two interest rate cuts from the current cash rate of 0.75%. There’s also a risk that the RBA will begin quantitative easing, which would have the likely effect of reducing bond yields and the level of borrowing over the medium to long-term. The question of whether and in what manner the RBA might proceed with QE will have a large bearing on home prices over the new year.

Second, we need to keep an eye on credit data to obtain an overall assessment of borrowing, less the repayments that households are making on their mortgages. To date, we’ve noticed the credit data upswing hasn’t been as strong as the increase in lending or in home values. The reason for this is a lot of households are still keeping up their repayments, despite recent interest rate cuts.

As a result of this, households are deleveraging, which is positive for financial stability. If, on the other hand, we detect that credit data is picking up quite significantly (particularly for investors) it may heighten the risk that APRA responds by introducing macroprudential tightening tools.

And third, we need to keep in mind the dynamics between housing supply and demand. Over the past six to twelve months building approvals and new home construction have fallen significantly. The drop was largely anticipated, due to the considerable run-up in housing construction and overall increase in market housing supply since 2014, but the recent fall presents a substantial risk for near-term supply.

Thanks in no small part to steady population growth over the years we still have a very strong demand for housing in Australia. However, if supply continues to trickle so slowly into the market, or building approvals remain sluggish, we risk a period of undersupply in Australian housing and home prices will likely continue to rise as a result.

Taking all of these factors into account, the overall picture for the Australian housing market over the next one to two years is that after initial and significant gains in Sydney and Melbourne, we should see prices start to stabilise – running at about 5% yearly growth over the near-term.


Author: Diana Mousina, Economist – Investment Strategy & Dynamic Markets, Sydney Australia

Source: AMP Capital 18 Dec 2019

Important notes: While every care has been taken in the preparation of this article, AMP Capital Investors Limited (ABN 59 001 777 591, AFSL 232497) and AMP Capital Funds Management Limited (ABN 15 159 557 721, AFSL 426455) (AMP Capital) makes no representations or warranties as to the accuracy or completeness of any statement in it including, without limitation, any forecasts. Past performance is not a reliable indicator of future performance. This article has been prepared for the purpose of providing general information, without taking account of any particular investor’s objectives, financial situation or needs. An investor should, before making any investment decisions, consider the appropriateness of the information in this article, and seek professional advice, having regard to the investor’s objectives, financial situation and needs. This article is solely for the use of the party to whom it is provided and must not be provided to any other person or entity without the express written consent of AMP Capital.